

5 Most Common Mistakes Homebuyers Make — and How to Avoid Them
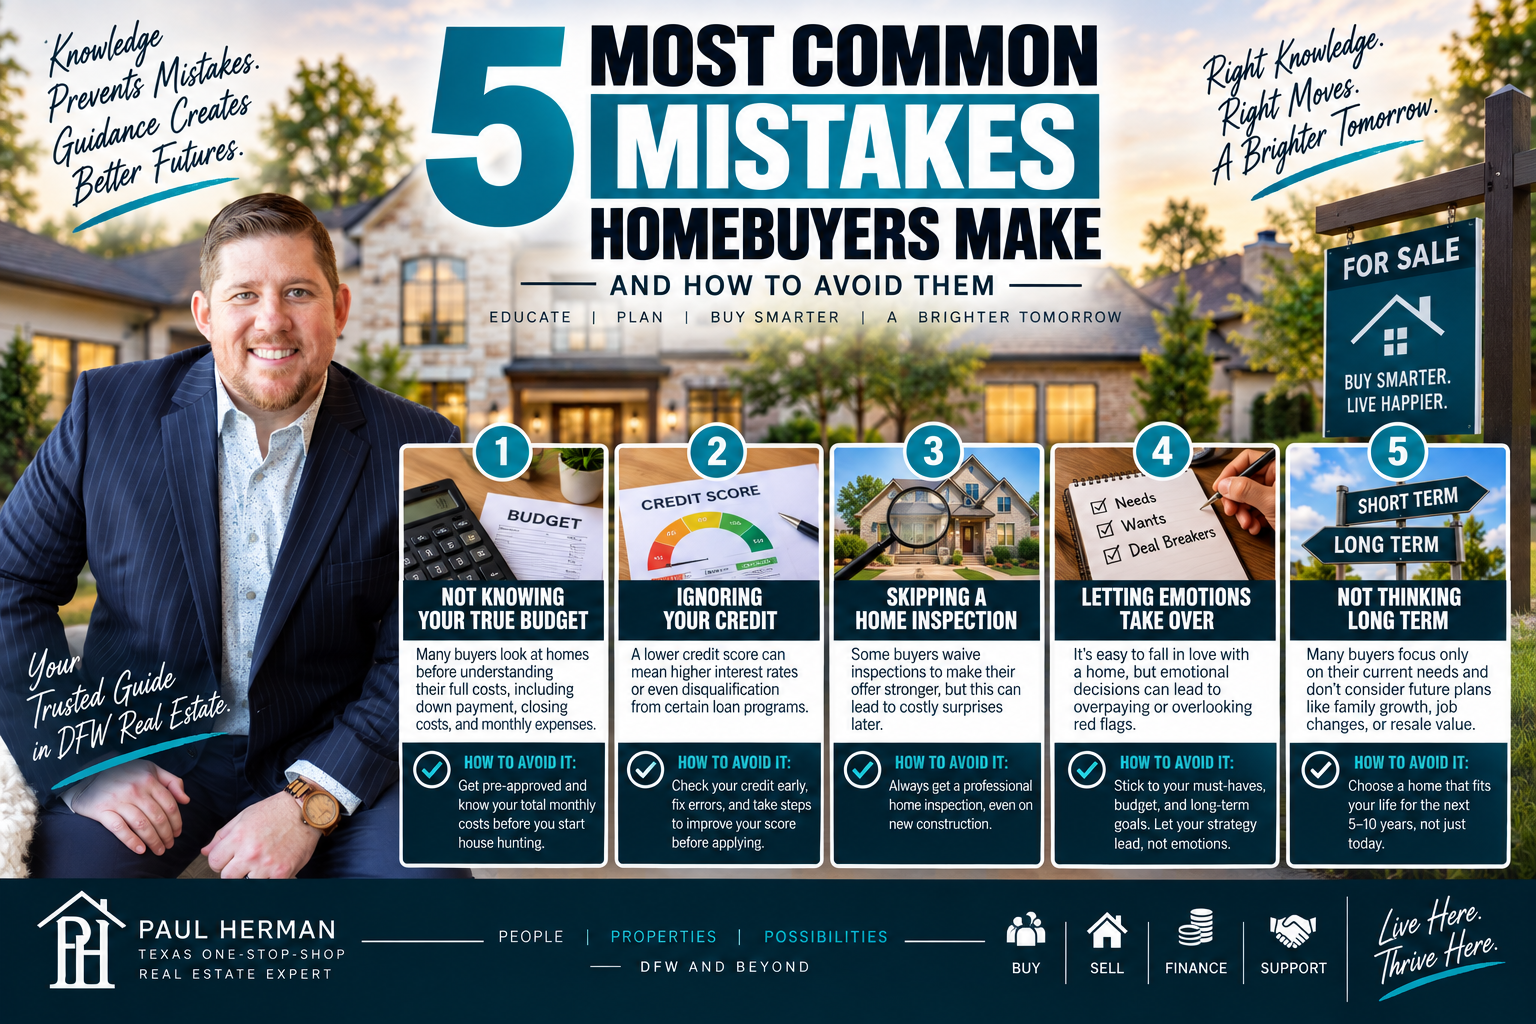
5 Most Common Mistakes Homebuyers Make — and How to Avoid Them
Buying a home is exciting, but it is also one of the largest financial decisions most people will ever make.
And here's something I've learned from working with buyers:
Most home-buying mistakes aren't made because someone intentionally made a bad decision.
They're usually made because the buyer didn't know what they didn't know.
Maybe they started looking at homes before understanding their finances. Maybe they focused too much on the purchase price instead of the monthly payment. Maybe they fell in love with a house and overlooked an expensive issue. Or maybe they made a financial decision during the loan process that created a problem right before closing.
That's exactly why I believe buyers need more than someone who simply opens doors.
They need a plan, education, and someone helping them look at the entire transaction.
Here are five of the most common mistakes I see homebuyers make—and how you can avoid them.
1. Looking at Homes Before Understanding Your Finances
This is probably one of the easiest mistakes to make.
You start scrolling through homes online.
You see one you love.
Then another.
Before long, you're scheduling showings without really knowing what your financing looks like.
I prefer to do things in the opposite order.
Before we seriously start shopping, I want my buyers to understand:
- Their estimated purchasing power
- Their comfortable monthly payment
- Down-payment options
- Estimated closing costs
- Property taxes
- Homeowners insurance
- HOA costs, when applicable
- Potential mortgage insurance
- Cash needed to close
- Emergency reserves after purchasing
And most importantly:
What can you comfortably afford—not simply what can you qualify for?
Just because a lender says you may qualify for a certain loan amount doesn't automatically mean you should spend that much.
How to Avoid This Mistake
Start with the financial conversation.
Get properly pre-approved and understand what different purchase prices could mean for your monthly payment and cash needed at closing.
Then build your home search around numbers you're comfortable with.
Your budget should determine your home search. Your home search shouldn't determine your budget.
2. Focusing Only on the Purchase Price
Imagine two homes are both listed for $450,000.
Does that mean they cost you the same amount every month?
Not necessarily.
One property could have significantly higher property taxes.
One could have an HOA.
One could potentially cost more to insure.
One may need a new roof or HVAC system soon.
Another may be more energy efficient and require very little immediate maintenance.
That's why I don't want my buyers evaluating homes based solely on:
"What's the sales price?"
I want them asking:
"What's the total cost of owning this home?"
Your housing expenses can potentially include your mortgage payment, property taxes, homeowners insurance, mortgage insurance, HOA dues, utilities, maintenance, and repairs.
How to Avoid This Mistake
Before making an offer, look at the complete financial picture.
This is especially important in Texas, where property taxes and insurance can represent a meaningful portion of your monthly housing expense.
A home that costs slightly more could sometimes make more sense financially than another property depending on taxes, insurance, condition, financing, and other expenses.
Don't just compare prices. Compare the overall cost of ownership.
3. Falling in Love With the House and Ignoring Potential Problems
This is where buying a home becomes emotional.
You walk inside.
Beautiful kitchen.
Perfect backyard.
Huge primary bathroom.
Exactly the flooring you wanted.
You're already imagining where the furniture will go.
Then you say:
"This is the one."
There's nothing wrong with getting excited about a home.
But I want my buyers to remain objective enough to evaluate what they're actually purchasing.
That beautiful kitchen doesn't tell us the condition of the:
- Roof
- HVAC system
- Foundation
- Plumbing
- Electrical system
- Windows
- Drainage
- Water heater
- Sewer line
- Other major components
And this is why inspections and proper due diligence are so important.
How to Avoid This Mistake
Enjoy the cosmetic features—but look beyond them.
When I'm touring a property with a buyer, I'm not simply looking at whether the house is beautiful.
I'm also thinking:
What concerns do I see?
What might need additional evaluation?
What could potentially become an expensive repair?
How does this property compare with others we've seen?
Does the location and layout make sense long term?
What could affect future resale?
Then, once under contract, use qualified inspectors and other appropriate professionals to help evaluate the property.
Fall in love with the home—but make the decision with your head too.
4. Making Major Financial Changes Before Closing
This is one mistake that can potentially turn an exciting home purchase into a major problem.
You're under contract.
Everything looks good.
Closing is a few weeks away.
So you decide to buy furniture for your new house.
The furniture store offers financing.
Or maybe you decide it's time for a new vehicle.
Or you open another credit card.
Stop.
Your mortgage approval is based on your financial profile.
Changes to your credit, debt, income, employment, or available funds may affect your loan qualification.
Mortgage lenders may verify information again before closing, so buyers should avoid assuming that an initial approval means nothing can change afterward.
How to Avoid This Mistake
While you're preparing to buy and especially while you're under contract, communicate with your mortgage professional before making significant financial changes.
Be careful about:
- Financing furniture
- Buying or leasing a vehicle
- Opening credit cards
- Increasing credit-card balances
- Taking personal loans
- Co-signing for someone
- Changing jobs
- Moving large amounts of money between accounts
- Making large cash deposits that may require documentation
That doesn't mean every financial change will prevent you from buying a home.
It means you should understand the potential impact before you do it.
My Simple Rule:
Before making a major financial decision during the mortgage process, make a phone call first.
A five-minute conversation could save you from creating an unnecessary problem.
5. Choosing a Home Without Thinking About the Future
Most buyers naturally think about what they need today.
But I encourage my clients to think beyond move-in day.
Ask yourself:
"Will this home still make sense for me five years from now?"
Your life can change.
You may:
- Change jobs
- Start or grow your family
- Begin working from home
- Travel more frequently
- Need additional space
- Have aging family members live with you
- Want different amenities
- Eventually turn the property into a rental
- Decide to sell and purchase another home
That's why location, floor plan, lot, community, accessibility, maintenance, and potential resale should all be part of the conversation.
You can change countertops.
You can replace flooring.
You can repaint walls.
You can't change where the house is located.
How to Avoid This Mistake
Don't ask only:
"Do I love this house today?"
Also ask:
"Does this property support where I think my life is going?"
Nobody can predict the future perfectly.
But thinking long term can help you make a more informed decision today.
BONUS MISTAKE: Trying to Do Everything Alone
There is an enormous amount of information available online.
That's a good thing.
Buyers today can research homes, neighborhoods, mortgage rates, property values, taxes, and virtually everything else from their phones.
But information and guidance aren't necessarily the same thing.
A home purchase can involve:
Real estate + mortgage financing + insurance + inspections + appraisal + title + contracts + negotiations + taxes + closing.
And these pieces often affect one another.
An inspection problem can become a negotiation issue.
An appraisal problem can become a financing issue.
An insurance problem can potentially become a lending issue.
A financing issue can affect your ability to close.
That's why the team around you matters.
You want professionals who communicate, educate you, identify potential problems, and help you understand your options.
What Do These 5 Mistakes Have in Common?
Almost all of them can be reduced with one thing:
Preparation.
The earlier we start planning, the more opportunities we have to address potential issues before they become problems.
That's why I don't believe the home-buying process should begin when we walk into the first house.
It should begin with a conversation.
Related Reading


Our mission is to provide exceptional customer service to our clients by taking the time to understand their unique needs and goals.

